Your Medicare Open Enrollment Checklist (Before December 7)
On October 15, Medicare open enrollment opens. You have until December 7 to make changes for 2027, which sounds like plenty of time, right up until it’s Thanksgiving, the grandkids are visiting, and the deadline is next week.
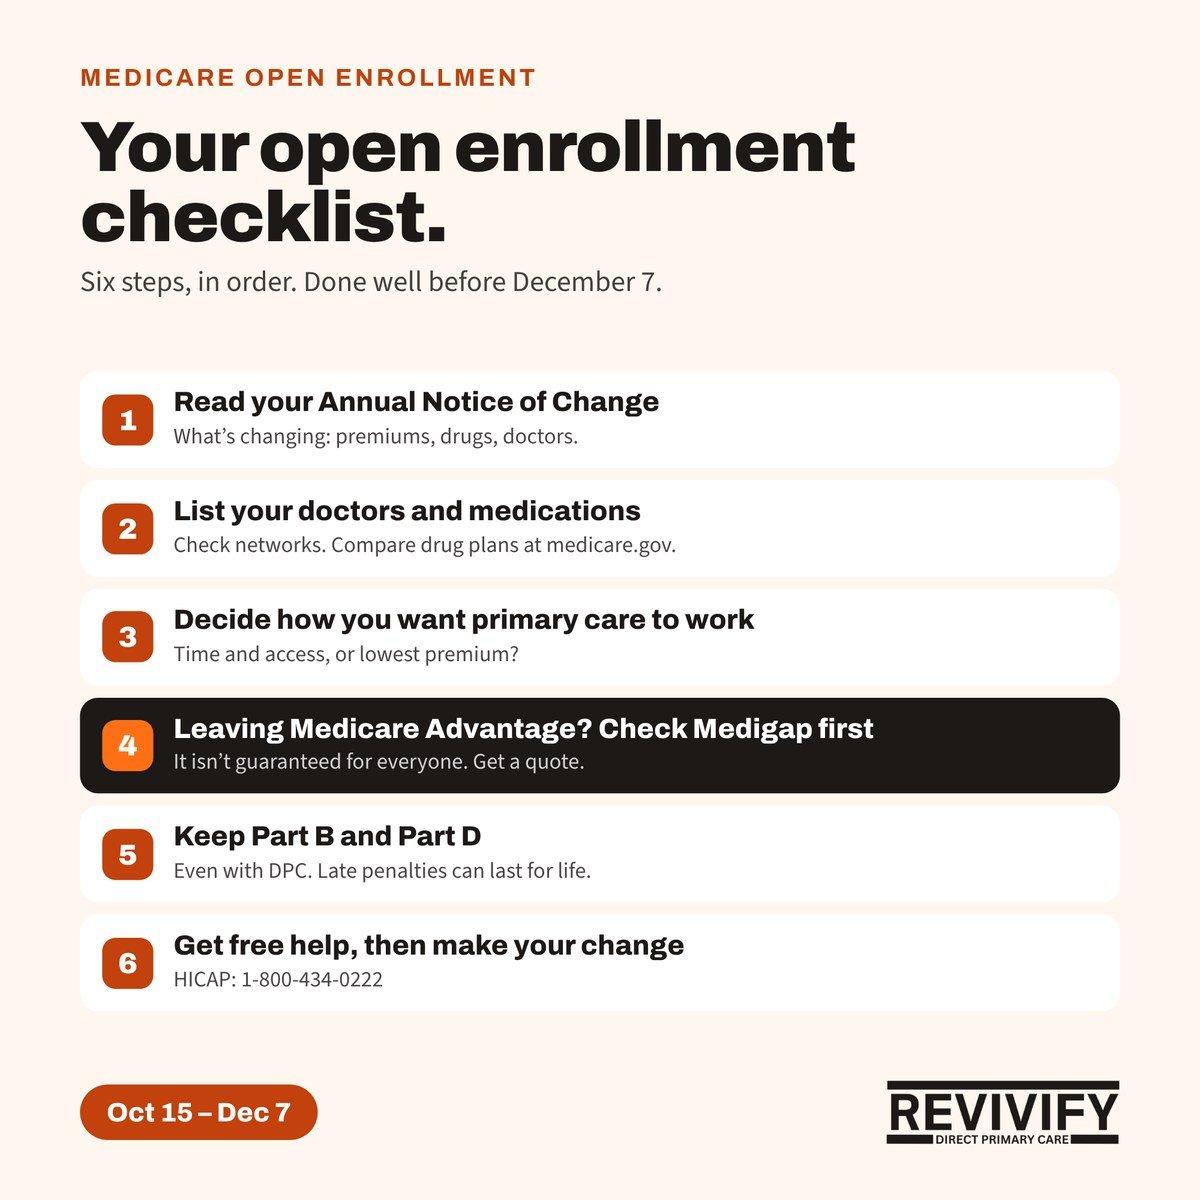
So let’s get organized now. This Medicare open enrollment checklist pulls together everything we’ve covered over the past week into six steps. Do them in order, and you’ll make your choice calmly, on purpose, and well before the deadline.
The Problem: Big Decisions, Made in a Hurry
Most Medicare mistakes aren’t caused by bad judgment. They’re caused by timing. Someone switches plans in a rush on December 6, then discovers in January that their specialist isn’t covered or a supplement isn’t available. The decision itself could have been fine. The order of operations wasn’t.
The Insight: Sequence Beats Speed
The key to a good open enrollment is doing things in the right order: understand what’s changing, decide what you want, check that you can actually get it, and only then make the switch. The checklist below follows that order.
Step 1: Read Your Annual Notice of Change
If you’re in a Medicare Advantage or Part D plan, your plan mailed you an Annual Notice of Change (ANOC) in September. It lists what’s changing next year: premiums, copays, the drug list, the pharmacy network and the doctor network. Spend 20 minutes with it. If you can’t find it, call the number on your plan card and ask for another copy.
Step 2: List Your Doctors and Your Medications
Write down every doctor and specialist you see, and every medication you take with its dose. If you’re in a Medicare Advantage plan, check that each doctor will still be in network next year. Then run your medications through Medicare’s Plan Finder at medicare.gov to compare drug plans. Plans change their premiums and drug lists every year, so it’s worth checking even if you were happy this year.
Step 3: Decide How You Want Primary Care to Work
This is the question most people skip. Do you want a doctor who has time for you, answers your texts and coordinates your care? Or is the lowest monthly premium your top priority, network rules and all?
If direct primary care appeals to you, remember the scorecard: Original Medicare with a Medigap supplement and a Part D plan is the cleanest fit. A Medicare Advantage PPO is workable. A Medicare Advantage HMO usually means paying for two primary care doctors.
Step 4: If You’re Leaving Medicare Advantage, Check Medigap First
This is the step that protects you from the most expensive surprise. Medigap supplements have no annual open enrollment. Outside of certain situations, insurers can ask health questions and decline you or charge you more.
Before you switch, get a Medigap quote and ask whether you qualify for a guaranteed right to buy. You may, if:
- You joined Medicare Advantage for the first time within the past 12 months (your “trial right”)
- Your Medicare Advantage plan is leaving your area or the market for 2027 (check your mail for a non-renewal letter)
- In California, your plan is raising its premium or copays significantly, cutting benefits, or dropping your doctor. These changes can give you a guaranteed right to a Medigap plan, starting with the same insurer. HICAP can tell you whether it applies to you.
If a supplement is available at a price that works, you’re in good shape. If not, a Medicare Advantage PPO may be the better path for now.
Step 5: Don’t Drop Part B or Part D
It bears repeating. If you join a DPC practice, keep Part B and keep a Part D plan. Part B pays for your specialists, imaging and outpatient care. Part D covers your prescriptions. Dropping either one can mean lifelong late-enrollment penalties.
Step 6: Get Unbiased Help, Then Make Your Change
HICAP, California’s free Medicare counseling program, will walk through your options with no sales agenda: 1-800-434-0222. A licensed broker can also help, especially with Medigap quotes. Once you’ve decided, make your change between October 15 and December 7. Your new coverage starts January 1.
And if you miss something? If you’re in Medicare Advantage on January 1, you’ll get one more chance to switch plans or move to Original Medicare between January 1 and March 31. (More on all the key dates here.)
Who This Is For
This checklist is for anyone on Medicare who wants to make a deliberate choice this fall, and anyone helping a parent do the same. Print it, put it on the fridge, and work through it over the next few weeks.
FAQ: “What If I’m Happy With My Current Plan?”
Then you may not need to do anything. Your plan renews automatically. Still, do Steps 1 and 2. Plans change every year, and it’s better to find out in October than in January.
The Revivify Difference
I won’t pick a plan for you, and I don’t sell insurance. What I will do is sit down with you, for as long as it takes, and explain how the plan you’re considering would work with your care. That’s what having time for patients means.
What’s Next
Open enrollment opens October 15. Next up: a one-page recap of the whole series. If you’d like to talk through how direct primary care would fit with your Medicare, learn about our membership or call us at 858-429-0099.
This post is for general education and isn’t insurance advice. Revivify doesn’t sell insurance, and direct primary care is not insurance.
← Back to all posts