Medicare Open Enrollment Dates You Can’t Afford to Miss
Quick quiz. When can you switch from a Medicare Advantage plan back to Original Medicare? If you said “during open enrollment,” you’re right. If you said “anytime,” you’re in good company, and you’re wrong. And if you said “I’ll figure it out when I need to,” this post is for you.
Medicare runs on deadlines. Miss one, and you can be stuck in a plan for a year, or pay a penalty for the rest of your life. Know them, and you have a surprising amount of freedom. Let’s walk through the Medicare open enrollment dates that matter this fall, plus a few lesser-known windows that can save you if you change your mind.
The Problem: Medicare’s Calendar Is Built for Insurers, Not People
Medicare has at least half a dozen enrollment windows, each with its own rules about who can use it and what you can change. Insurers know these cold. Most patients don’t, and the marketing doesn’t help: every ad says “call now,” but none of them mention that some decisions are much harder to undo than others.
The result? People make a big change in a hurry, then discover in February that their doctor isn’t covered, or that going back isn’t as simple as it sounded.
The Insight: Some Doors Swing Both Ways, and Some Don’t
The single most useful thing to understand about Medicare deadlines is this: switching into Medicare Advantage is easy. Switching out to Original Medicare is easy too. But getting a Medicare Supplement (Medigap) policy to go with Original Medicare, after your first few months on Medicare, can be hard, depending on your health.
Keep that in mind as we go through the dates. It’s the reason the rest of this calendar matters.
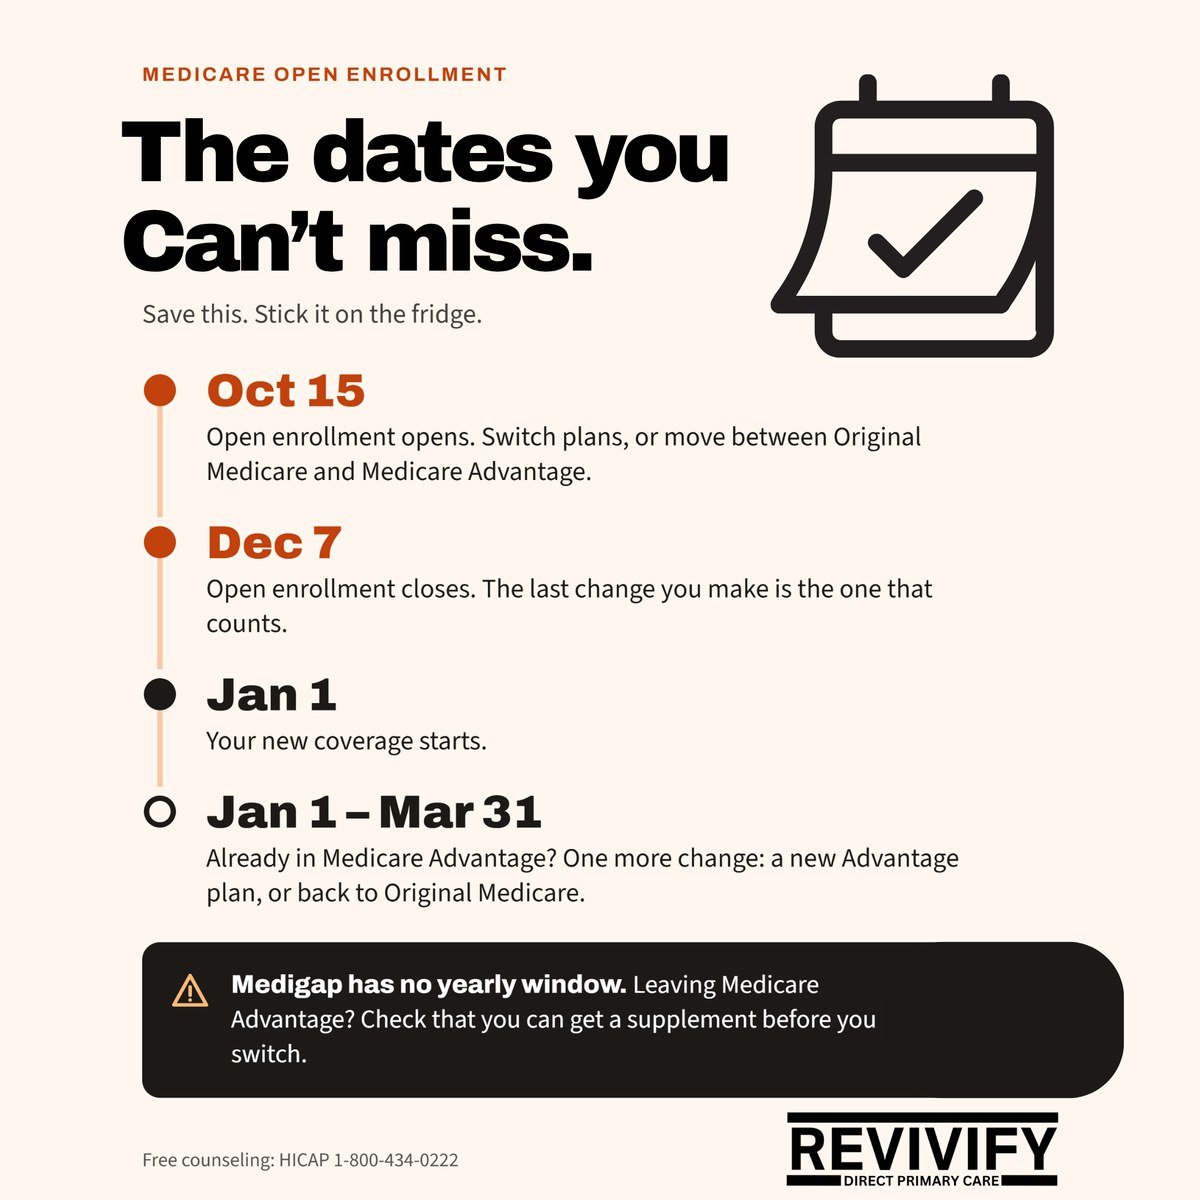
October 15: Open Enrollment Begins
This is the big one. From October 15 through December 7, anyone already on Medicare can:
- Switch between Original Medicare and Medicare Advantage, in either direction
- Change from one Medicare Advantage plan to another
- Join, change or drop a Part D drug plan
You can make changes as many times as you want during this window. Only the last one you make before December 7 counts.
December 7: Open Enrollment Ends
This is the hard stop. After December 7, your choice is locked in for the coming year, with a few exceptions we’ll cover below. Don’t wait until the last weekend. Plan websites crash, broker phone lines jam, and rushed decisions are rarely good ones.
January 1: Your New Coverage Starts
Whatever you chose during open enrollment takes effect on January 1, 2027. New ID cards should arrive in late December. Keep your old card until the new year, then shred it.
January 1 to March 31: The Medicare Advantage Do-Over
This is the window most people have never heard of. If you’re in a Medicare Advantage plan on January 1, you get one more chance between January 1 and March 31 to either switch to a different Medicare Advantage plan or drop Medicare Advantage and return to Original Medicare (and pick up a standalone Part D drug plan).
You get one change during this period, and it takes effect the first day of the following month. So if you switch on January 20, your new coverage starts February 1.
Note what this window does not do: it doesn’t let someone on Original Medicare move into Medicare Advantage. It’s an exit and swap door for people already in Advantage plans.
Medigap: No Annual Window, and That Matters
Here’s where people get tripped up. Medigap (Medicare Supplement) policies don’t have an annual open enrollment like everything else. You get a one-time, six-month window that starts when you’re 65 or older and enrolled in Part B. During that window, insurers must sell you any Medigap policy they offer, regardless of your health.
After that window closes, an insurer can usually ask health questions and turn you down or charge you more. There are exceptions:
- Trial right. If you joined Medicare Advantage for the first time and want to go back to Original Medicare within the first 12 months, you generally have a guaranteed right to buy Medigap.
- Plan leaving your area. If your Medicare Advantage plan is leaving the market or your county, you typically get a guaranteed right to buy certain Medigap plans. Several insurers are pulling back for 2027, so check your mail for a non-renewal letter.
- California’s birthday rule. If you already have Medigap, California gives you 60 days each year starting on your birthday to switch to another Medigap plan with equal or lesser benefits, no health questions asked.
The takeaway: if you’re in Medicare Advantage today and thinking about moving to Original Medicare, check your Medigap options before you switch, not after.
The Other Windows Worth Knowing
- Turning 65? Your Initial Enrollment Period is seven months long: the three months before your birthday month, the month itself, and the three months after.
- Missed Part B? The General Enrollment Period runs January 1 to March 31, but late-enrollment penalties can apply for life.
- Big life change? Moving, losing employer coverage, or qualifying for extra help can open a Special Enrollment Period at other times of the year.
Who This Is For
If you’re on Medicare and have ever thought “I’ll just change it next year,” this calendar is for you. It’s especially important if you’re in a Medicare Advantage plan and considering a move to Original Medicare, or if you’re thinking about joining a direct primary care practice and want your coverage set up to match.
Myth-Busting: “I Can Always Switch Back”
You can always switch plans back during the right window. What you can’t always get back is a Medigap policy at a fair price. That’s not a reason to panic. It’s a reason to sequence your decisions: find out what Medigap would cost you, then make the switch.
The Revivify Difference
We’re not an insurance agency, and I won’t tell you which plan to buy. What I can do is explain how each type of coverage works with direct primary care, so you walk into your broker or HICAP appointment knowing what to ask. HICAP is California’s free Medicare counseling service, and you can reach them at 1-800-434-0222.
Put the Dates on Your Fridge
Save these dates and stick them on the fridge. Next up: what Parts A, B, C and D actually mean, in plain English. Missed the first post? Start here. Want to talk through how DPC would fit with your Medicare? Learn about our membership or give us a call at 858-429-0099.
This post is for general education and isn’t insurance advice. Revivify doesn’t sell insurance, and direct primary care is not insurance.
← Back to all posts