San Diego’s 13% Covered California Hike: The Smarter Combo
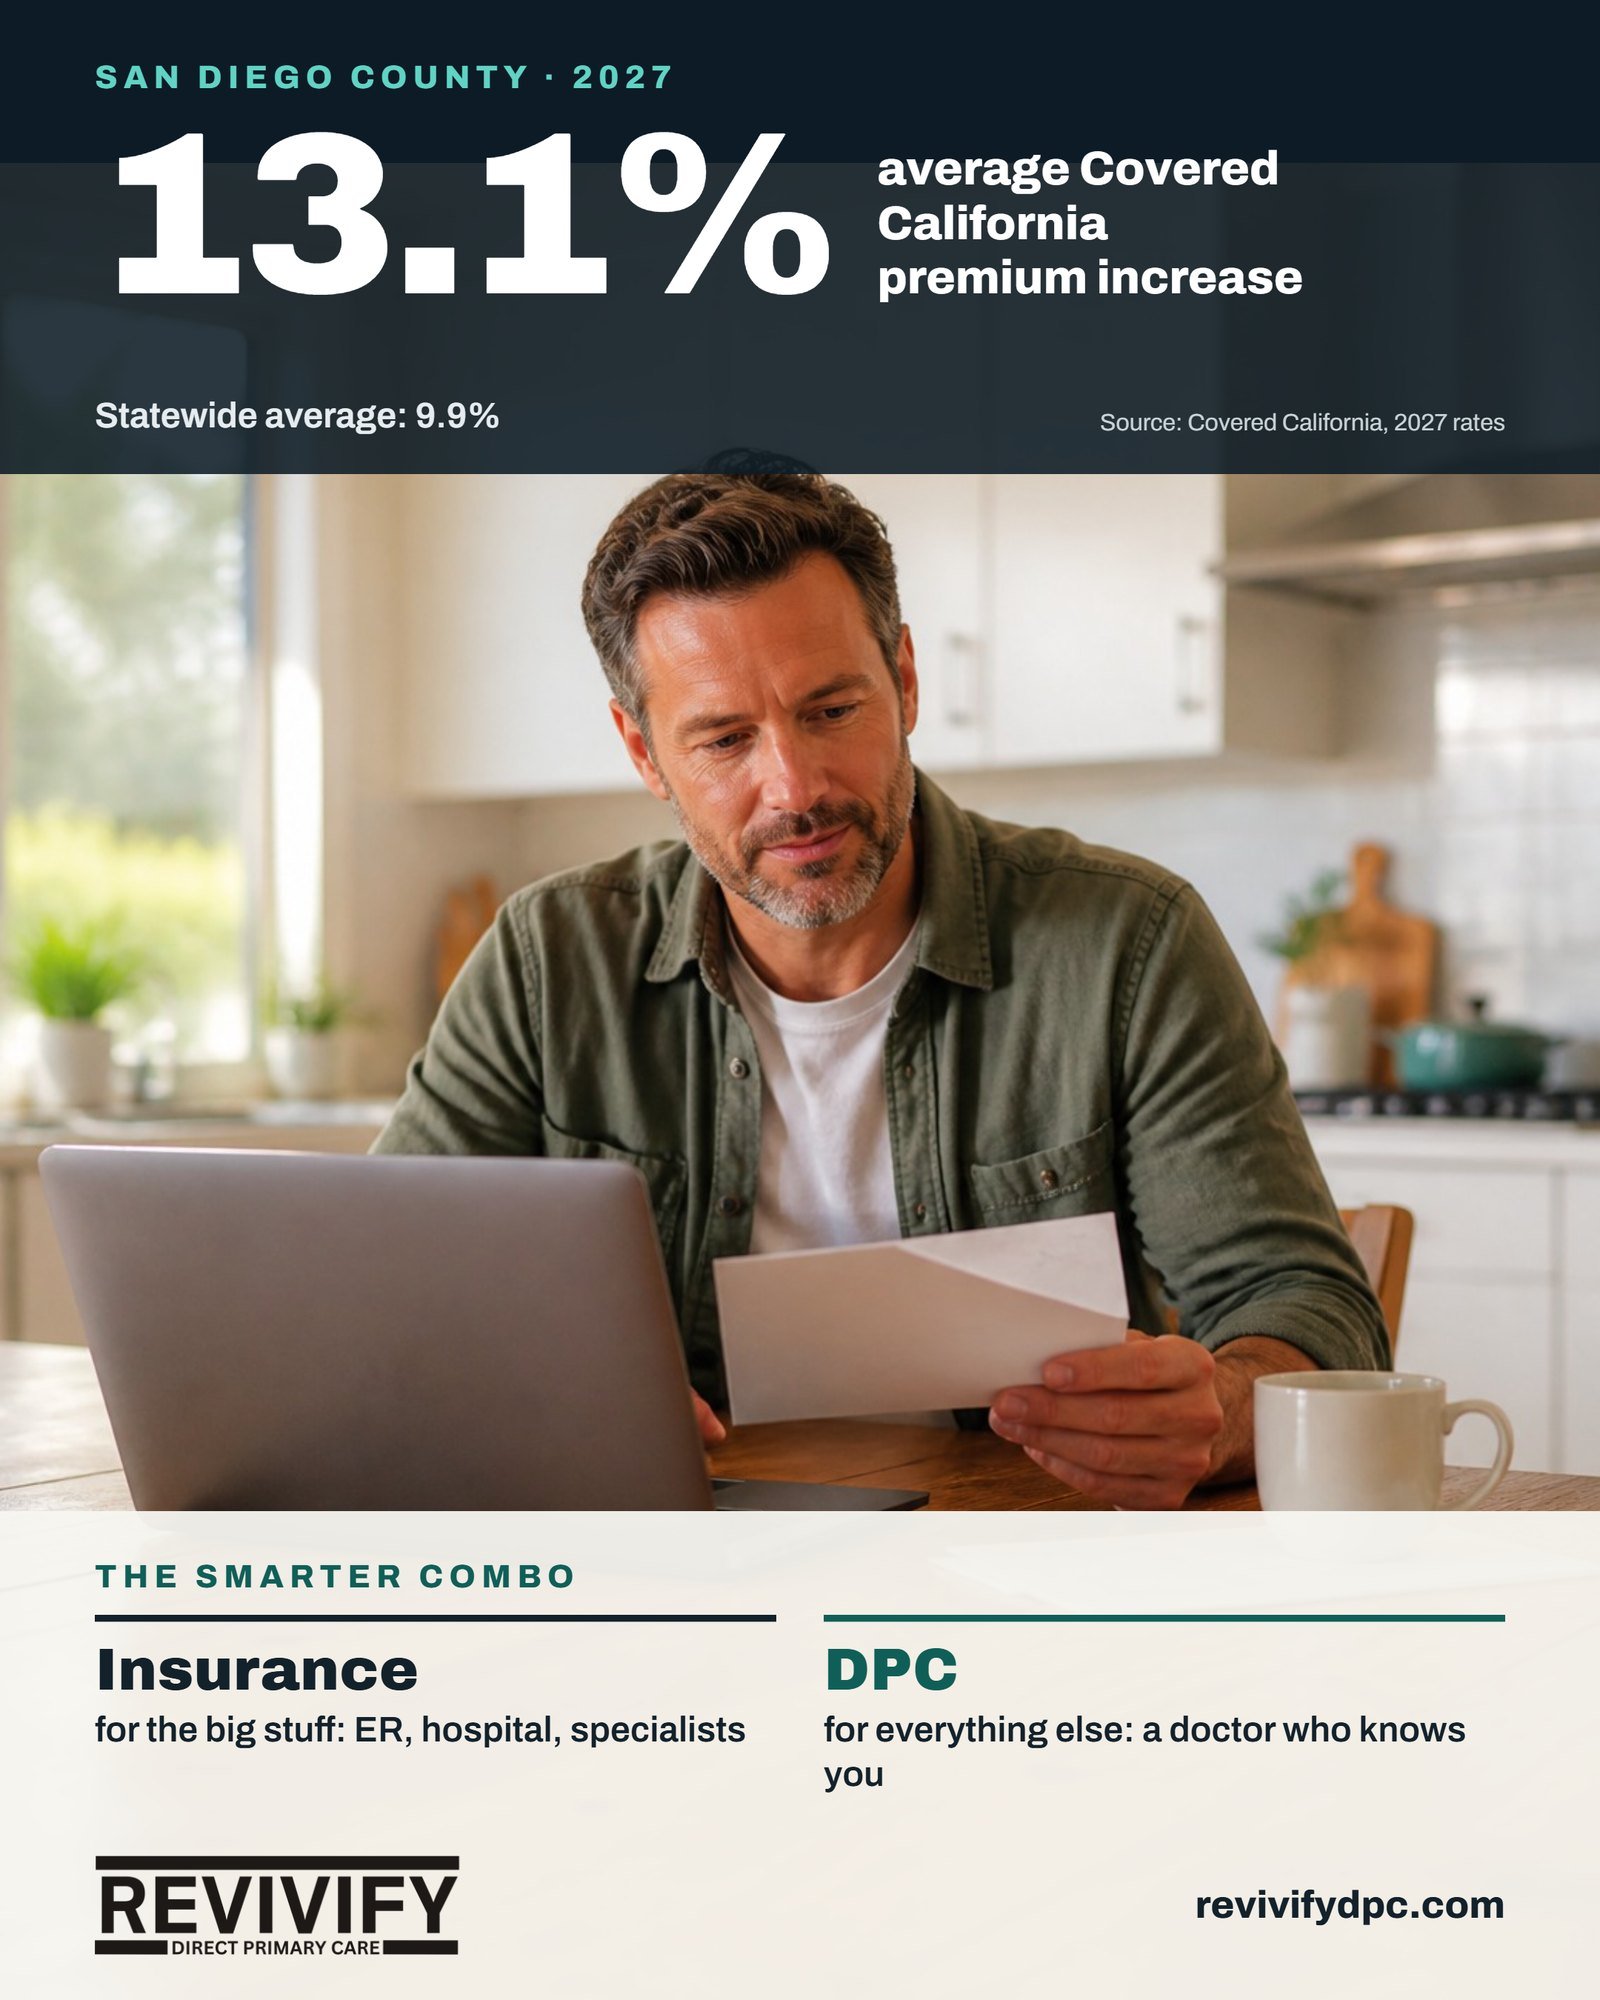
If a renewal letter from your health plan is sitting on your kitchen table right now, you’re not alone, and you’re not imagining it. Covered California 2027 rates are going up an average of 9.9% statewide. Here in San Diego County, the average increase is 13.1%.
So before you sign the renewal and move on with your life, let’s talk about what’s going on, who actually feels it, and a smarter way to put your health care dollars to work. Spoiler: it involves asking your insurance to do less, not more.
What’s Happening With Covered California 2027 Rates
Covered California announced its 2027 plans and rates this summer. The statewide weighted average increase is 9.9%, which is actually lower than the national picture. Across the country, insurers proposed a median increase of about 14% for ACA marketplace plans.
San Diego didn’t get off so easy. Our region’s average increase is 13.1%, the second highest of California’s 19 rating regions. Only the Imperial, Inyo and Mono County region came in higher.
Why the jump? Covered California points to the rising cost of health care and prescriptions. Federal changes play a part too. The enhanced federal premium tax credits that helped millions of people afford coverage expired at the end of 2025 and weren’t renewed. When some people drop coverage, the people who stay tend to be the ones who need more care, and that pushes premiums up for everyone in the pool.
A few dates to know. Current members could renew or switch plans starting October 1. Open enrollment for everyone runs November 1 through January 31, 2027. The new rates take effect January 1.
The Problem: Who Actually Feels the Increase
Here’s the honest part, because the headline number doesn’t hit everyone the same way.
Most Covered California members get financial help. According to Covered California, about 60% of enrollees will see no increase in their monthly premium in 2027, thanks to federal tax credits and an expanded state subsidy program for lower-income Californians. If that’s you, good news: your bill may barely move.
The people who feel the full increase are the ones who don’t qualify for help. When the enhanced credits expired, the “subsidy cliff” came back. If your household income is above 400% of the federal poverty level (about $62,600 for a single person in 2026), you get no federal premium help at all. You pay the full sticker price, increase included. The same goes for anyone who buys an individual plan directly from an insurer instead of through Covered California.
In San Diego, that’s a lot of people: self-employed professionals, small business owners, early retirees who aren’t on Medicare yet, gig workers, and families whose income looks comfortable on paper until they see what rent and child care cost here.
And the frustrating part isn’t only the premium. It’s that you can pay more every year and still wait weeks to see your doctor, still get a 10-minute visit, and still owe a copay or the full cost of the visit until you hit your deductible.
The Insight: Stop Asking Insurance to Be Your Doctor
Insurance is a great tool for one job: protecting you from big, expensive, unpredictable events. The car accident. The appendix that picks a Tuesday to quit. The cancer diagnosis nobody plans for. That’s what you’re really buying when you buy coverage, and you should never go without it.
Primary care is a different animal. It’s predictable, frequent and relatively inexpensive: checkups, sinus infections, blood pressure follow-ups, a sprained ankle, refills, the “is this mole weird?” question. Running all of that through insurance means paperwork, copays, deductibles and a system that pays your doctor more for seeing more people faster.
So what if you split the job in two? Let insurance cover the big stuff. Let a direct primary care membership cover the everyday. That’s the combo, and for a lot of people it’s a smarter use of the same dollars.
Step 1: Shop Before You Auto-Renew
Whatever you decide, don’t let your plan renew on autopilot. Prices vary a lot from one insurer to the next.
Here’s a number that surprised me. Covered California estimates that if San Diego enrollees shopped and switched to the lowest-cost plan in their same metal tier, their average increase would drop from 13.1% to about 2.8%. That’s a big difference for an hour of comparison shopping.
Insurers’ increases also vary statewide. Kaiser Permanente’s average is 6.7%, Sharp Health Plan’s is 12.3%, Blue Shield of California’s is 12.5%, Anthem Blue Cross’s is 13% and Health Net’s is 13.2%. Your exact numbers will depend on your age, ZIP code and plan, so run your own comparison at CoveredCA.com. Check that the doctors, hospitals and prescriptions you care about are covered before you switch.
Step 2: Match the Plan to Its Job
If insurance is mainly there to protect you from the big stuff, the plan you need may look different from the one you’ve been buying.
- Bronze plans have lower premiums and higher deductibles. They make the most sense when you mostly want protection from a major event and your everyday care is handled somewhere else.
- Silver plans can be a better deal if your income qualifies you for extra cost-sharing help, which lowers your deductible and copays.
- Gold and Platinum plans cost more each month but less when you use care. They can make sense if you expect a surgery, a pregnancy or a lot of specialist visits this year.
There’s no single right answer. I’m a doctor, not an insurance agent, so if you’re unsure, a certified Covered California enroller can walk you through your options for free.
Step 3: Add Direct Primary Care for the Everyday
This is where direct primary care comes in. Instead of billing insurance, you pay your doctor a flat monthly membership. At Revivify, that’s $129 a month for adults, and here’s what it covers:
- Unlimited visits. Come in as often as you need. No copays, no deductible, no surprise bills from my office.
- Time. Same or next-day appointments that last at least 30 minutes. Bring the whole list.
- Direct access. Text, call or video with me directly. That question at 9 p.m.? Send it.
- In-office generic medications at a fraction of retail prices, often less than a typical insurance copay.
- Discounted labs and imaging at negotiated cash prices.
- A quarterback. When you do need your insurance for a specialist, imaging or a hospital stay, I help coordinate it and make sense of the results.
Put together, the combo looks like this: a plan that fits your needs and budget, protecting you from the big stuff, plus a doctor who actually knows you, handling everything else.
The New HSA Wrinkle That Makes the Combo Even Better
A federal law passed in 2025 changed the rules on health savings accounts (HSAs), and the changes took effect January 1, 2026.
- Bronze and catastrophic marketplace plans now qualify for an HSA. In the past, many of them didn’t. Now, if you’re enrolled in one, you can open and contribute to an HSA.
- Direct primary care no longer disqualifies you from an HSA. Before 2026, a DPC membership could knock you out of HSA eligibility. Now, qualifying arrangements are allowed.
- DPC membership fees can be paid with HSA dollars. The law allows up to $150 a month for an individual and $300 a month for a family. Revivify’s $129 adult membership fits under that limit.
In plain English: you can pair a lower-premium Bronze plan with an HSA, put pre-tax money in, and use it to pay for your DPC membership. Your tax situation is your own, so check with your accountant or tax professional on the details.
What This Can Look Like
Here’s a hypothetical. Picture a self-employed consultant in Rancho Bernardo, mid-40s, earning just over the subsidy cutoff. Her Silver plan renewal just jumped, and she mostly uses it for a yearly physical, a couple of sick visits and a few refills.
She shops on CoveredCA.com and moves to a Bronze plan, which lowers her premium. She opens an HSA. She joins a DPC practice and pays the membership from her HSA. Her sick visits, refills and follow-ups now happen by text or same-day appointment, with no copay. If she ever needs an MRI, a specialist or a hospital, her insurance is still there.
Will that math work for everyone? No. But for many people who pay full price and use primary care far more than anything else, it’s worth running the numbers.
Who This Is For
This approach is worth a look if you buy your own insurance and don’t qualify for much financial help, you’re generally healthy or managing a few chronic conditions with regular checkups and refills, and you’re tired of waiting weeks for a short visit. It’s a natural fit for self-employed people, small business owners, early retirees and families who want a doctor they can actually reach. If you’re 65 or older, the Medicare version of this combo works a little differently, and I covered it in Original Medicare + Direct Primary Care.
FAQ: “Can I Skip Insurance and Just Use DPC?”
No, and I’d never recommend it. Direct primary care is not insurance. It won’t pay for a hospital stay, surgery, an emergency room visit or a specialist. Those are exactly the expensive surprises insurance exists for. The point of the combo isn’t to drop coverage. It’s to stop paying insurance to do a job it does poorly, so the coverage you keep can do the job it does well.
The Revivify Difference
I spent 20 years caring for everyone from high school athletes to Olympians, and the lesson that stuck is that the relationship is the medicine. Revivify DPC is capped at 300 members, so you get unhurried visits, a doctor who answers your texts, and help navigating the insurance side when you need it. I’m not trying to replace your insurance. I’m trying to make sure you actually get care while you have it.
What to Do Before January 31
Open your renewal letter. Compare plans at CoveredCA.com before January 31. And if you want to see how direct primary care would fit with the plan you choose, learn about our membership or call us at 858-429-0099.
This post is for general education and isn’t insurance, tax or financial advice. Revivify doesn’t sell insurance, and direct primary care is not insurance. Rate figures are Covered California’s 2027 averages; your own premium will depend on your age, location, income and plan.
← Back to all posts